Life Insurance Australia :: News
SHARE

Share this news item!

New Broker Code Raises the Bar for Strata Insurance Transparency

From January 2027, owners corporations should see clearer disclosure around broker authority, commissions and related benefits

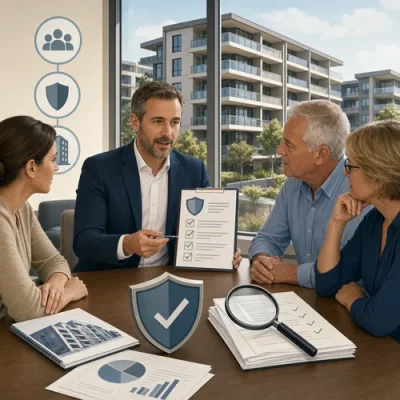
New Broker Code Raises the Bar for Strata Insurance Transparency?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

The final 2027 Insurance Brokers Code of Practice has put strata insurance transparency firmly in the national spotlight, with new expectations for how brokers disclose remuneration and confirm their authority when arranging cover for owners corporations.
Released by the National Insurance Brokers Association in October 2026 and due to take effect on 1 January 2027, the code is not strata legislation, but it will shape how code-subscribing brokers deal with one of the sector’s most sensitive renewal issues: who is being paid, by whom, and on what basis.

The most relevant change for strata communities is that remuneration disclosure is being extended across strata insurance services provided to an owners corporation, whether or not the client is treated as a retail client. This matters because many strata schemes sit in a practical grey zone: individual lot owners pay levies that fund the premium, but the insurance is usually arranged at owners corporation level, often through a strata manager and an insurance broker.

The code also strengthens the focus on authority. Where a broker is engaged through a strata manager or another party, the broker is expected to take reasonable steps to confirm that the appointment has the owners corporation’s authority. For committees, that makes renewal governance more than a paperwork exercise. Minutes, instructions, tender records and disclosure documents may become increasingly important if there is later a dispute about how the policy was arranged.

In practical terms, owners corporations may wish to look for clearer answers to several questions before renewal decisions are made:

  • What commission, fee, rebate or other benefit is being received by the broker?
  • Is any amount being paid or shared with the strata manager or another authorised party?
  • Is the amount shown in dollars, or is the basis of calculation clearly explained?
  • Has the owners corporation formally authorised the broker appointment?
  • Do the renewal documents explain the options considered, not just the recommended placement?

The change does not tell an owners corporation which strata insurance policy to choose, nor does it remove the need to consider cover limits, exclusions, excesses, claims history, building defects and catastrophe exposure. It is also important to recognise the code’s limits: it is a professional code for subscribing brokers, not a complete replacement for state and territory strata laws, Australian financial services obligations or owners corporation decision-making duties.

Even so, the timing is significant. Strata insurance has faced scrutiny over affordability, conflicts, disclosure and claims outcomes for several years. The new code suggests the market is moving towards a more documentable standard of trust. For lot owners, the practical benefit should be better visibility. For committees, the lesson is to treat disclosure as part of risk management, not as a formality left until the premium invoice arrives.

Published:Wednesday, 4th Nov 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Isuzu Recall Puts Software Risk on the Insurance Radar
05 Nov 2026: Paige Estritori
A fresh Australian Government vehicle recall for selected Isuzu MY25 trucks is a timely reminder that modern heavy vehicle risk is no longer limited to tyres, brakes, steering, driver behaviour or road conditions. Software faults can also create safety exposures that matter for fleet operations, incident investigations and insurance conversations. - read more
Delayed Insurance Inquiry Keeps Tradie Cover Issues on the Table
05 Nov 2026: Paige Estritori
A federal parliamentary inquiry into small business insurance has pushed its reporting timetable into early 2027, extending the wait for recommendations that may shape future debate on affordability, availability and regulation. For Australian tradespeople, the delay matters because the inquiry is examining the commercial insurance lines many small operators rely on daily, including public liability, professional indemnity, cyber risk and business interruption cover. - read more
Why Claims Communication Is Back in the Spotlight
05 Nov 2026: Paige Estritori
A new Life Code Compliance Committee inquiry has put fresh attention on the way life insurers manage longer-running income protection insurance and total and permanent disability claims, finding that clearer communication and earlier information requests could reduce avoidable stress for people waiting on claim decisions. - read more
New Isuzu Truck Recall Highlights a Claims Evidence Issue
05 Nov 2026: Paige Estritori
A fresh safety recall affecting 3,710 Isuzu MY25 trucks is a timely reminder that modern truck insurance risk is not only about driver behaviour, road conditions or workshop servicing. Software, trailer systems and electronic braking signals can all become part of the evidence trail if an incident occurs. - read more
Mental Health Cover Debate Now Matters for Business Protection
05 Nov 2026: Paige Estritori
Australia’s life insurance sector is moving into a detailed debate over how mental health conditions should be treated in disability-style cover, and the outcome could matter for business owners who rely on insurance to protect income, debt and operational continuity. - read more


Life Insurance Articles

A Millennial's Guide to Life Insurance
For many millennials, navigating the complexities of personal finance and future planning can feel like a bewildering journey. Among these financial responsibilities, life insurance emerges as a paramount consideration. More than just a safety net, life insurance can be the cornerstone of a sound financial strategy, providing peace of mind for both the policyholder and their loved ones. - read more
How life insurance claims work in Australia
A life insurance claim can feel difficult to navigate at an emotional time. This guide explains the usual steps beneficiaries follow in Australia, the documents commonly requested, how insurer assessment works, what may cause delays, and where to seek help if a claim is disputed. - read more
Term Life and Whole Life Insurance in Australia: What the Terms Mean
A plain-English guide to term life insurance, whole life insurance and the main types of personal life insurance Australians commonly compare, including life cover, TPD, trauma cover and income protection. - read more
Common Mistakes to Avoid When Comparing Life Insurance Policies
Choosing the right life insurance policy is one of the most important decisions for Australians, especially for those who are middle-aged or older. Life insurance provides financial security for your loved ones in the event of your passing, ensuring that they are not burdened with financial hardships. - read more
How Life Insurance Premiums Are Calculated in Australia
Life insurance premiums in Australia can vary widely because insurers assess personal, policy and underwriting factors differently. This guide explains the main cost drivers, including age, health, smoking status, occupation, cover amount, premium structure and policy options. - read more

Start Here !
life insurance
Apply now for your free Insurance assessment and price comparisons!

Start Here:

Life Insurance Type:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Subrogation:
The process by which an insurance company seeks to recover the amount paid to the policyholder from a third party responsible for the loss.