Silica Duties Are Now an Insurance Issue for Trade Businesses
Why dust controls, records and policy wording deserve a closer look
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Australia’s sharper focus on crystalline silica is moving beyond the engineered stone ban and into the everyday work of many trade businesses.
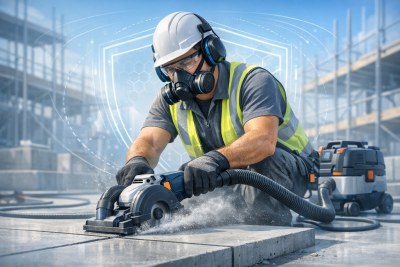
Cutting, grinding, drilling, chasing, polishing or demolishing materials such as concrete, bricks, pavers, tiles and stone can create respirable dust, and regulators are continuing to emphasise controls, supervision and evidence of safe work practices.
For tradies, this is not only a work health and safety issue. It can also affect how insurers view risk, how claims are assessed and what information a business may need to provide at renewal. A small contractor that can show practical controls, such as wet cutting, on-tool extraction, suitable respiratory protection, training records and maintenance logs, is in a stronger position than one relying on informal habits.
The insurance connection is clearest where illness, injury or third-party exposure is alleged. Workers compensation arrangements, income protection, management liability, statutory liability and public liability can all raise different questions depending on who was exposed, where the work occurred and whether the business followed required controls. Cover is never a substitute for compliance, but poor documentation can make an already difficult claim more complicated.
Trade businesses should also remember that silica risk is not limited to large construction sites. A sole trader cutting bathroom tiles, a landscaper working with pavers, a concreter grinding slab edges or an electrician chasing walls can all create exposures. Subcontracting can add another layer, because head contractors and principals may ask for proof of insurance, safe work method statements, dust management procedures and evidence that workers have been trained.
Practical steps to consider include:
reviewing which tasks create dust and whether safer methods are available;
checking that equipment, extraction systems and masks are suitable and maintained;
keeping training, fit-testing, incident and maintenance records in one place;
confirming who is responsible for controls when working under another contractor;
reading policy exclusions, notification obligations and occupation descriptions before renewal.
The broader lesson is that insurers increasingly want to understand how a trade business manages known risks, not just what trade category appears on a proposal form. Clear procedures and accurate disclosure can help avoid surprises later.
As silica regulation becomes part of routine site management, tradies should treat dust controls as part of business continuity. The right insurance settings matter, but they work best alongside safe systems, good records and a realistic understanding of the work being performed.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
Australia's construction sector remains under pressure, with recent insolvency figures continuing to show building and construction as one of the most exposed parts of the economy. Higher material costs, tight margins, labour shortages, delayed payments and fixed-price contract stress have all contributed to a tougher operating environment for builders, subcontractors and project owners. - read more
Recent transport industry sales updates point to a more selective new-truck market, with operators weighing replacement timing against finance costs, emissions planning, availability and contract confidence. For truck businesses, that matters well beyond the showroom. A change in buying momentum can flow through to vehicle values, repair economics, insurer appetite and the way fleets should set insurance sums before renewal. - read more
Fresh small business cyber warnings are a practical reminder that digital risk is no longer just a concern for large companies with complex IT systems. For Australian tradespeople, the most damaging cyber incident may be far simpler: a fake invoice, altered bank details, a compromised email account or a scam message that looks like it came from a supplier, builder, real estate agent or client. - read more
ASIC’s continuing focus on superannuation member services has put another practical issue in front of Australian workers: insurance inside super is not just about whether cover exists, but whether members can understand and use it when they need help. Recent regulatory attention on trustee administration, communication and claims support is a timely reminder for anyone relying on salary continuance or income protection benefits through their fund. - read more
Recent transport industry reporting has again highlighted growing interest in Performance Based Standards vehicles and other high-productivity truck combinations across Australia. For operators, the attraction is clear: fewer trips, better payload efficiency and stronger productivity on approved routes. For insurers, however, the shift is not simply a matter of adding another truck to the schedule. PBS combinations can alter exposure across vehicle value, route compliance, load responsibility, driver capability and recovery after an incident. - read more
Life insurance is an essential safety net for families, providing financial security when it's needed the most. As your family grows, the importance of having a well-structured life insurance policy becomes even more critical. In the busy lives we lead today, it’s easy to overlook this crucial aspect of financial planning. However, ensuring your coverage meets your family's evolving needs is vital. - read more
Life insurance can help provide a financial safety net for the people who depend on you. The right cover amount is not a single fixed figure: it depends on your income, debts, family responsibilities, future goals, savings and the type of policy you choose. - read more
The digital age has fundamentally transformed how we approach almost every aspect of our lives, including the way we shop for life insurance in Australia. Gone are the days when one had to schedule meetings with insurance agents or flip through pamphlets to understand life insurance policies. Today, obtaining life insurance quotes online has become the norm, offering a hassle-free and incredibly accessible platform for individuals to safeguard their financial future. - read more
A life insurance claim can feel difficult to navigate at an emotional time. This guide explains the usual steps beneficiaries follow in Australia, the documents commonly requested, how insurer assessment works, what may cause delays, and where to seek help if a claim is disputed. - read more
For many millennials, navigating the complexities of personal finance and future planning can feel like a bewildering journey. Among these financial responsibilities, life insurance emerges as a paramount consideration. More than just a safety net, life insurance can be the cornerstone of a sound financial strategy, providing peace of mind for both the policyholder and their loved ones. - read more
Start Here !
Apply now for your free Insurance assessment and price comparisons!
Knowledgebase
Surrender Value: The amount of money an insurance policyholder will receive if they voluntarily terminate the policy before it matures.




No comments yet. Be the first to share your thoughts.