Life Insurance Australia :: Articles

Public Liability, Product Liability and Professional Indemnity Insurance

What are public, product, and professional liability insurances?

Public Liability, Product Liability and Professional Indemnity Insurance

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

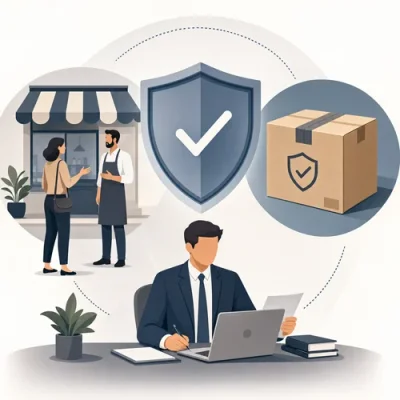
Business liability insurance provides protection for your business against the cost of litigation and claims resulting from third party damages or bodily injuries caused due to negligence of your business. In this article we examine the three main types of business liability insurances and how they may apply to your business.

To protect aginst the liabilities that a business can face, the three main types of business liability insurances are

  • public liability insurance,
  • product liability insurance and
  • professional indemnity insurance.

The above mentioned business insurance types differ from one another, but each has it's own importance in protecting the business from liabilities.

Hence, it is very important for businesses to safeguard their investment and to consider the three policies based on the type and need of their business.

Before deciding on what to take you shoukd understand the differences between them.

Public liability insurance

Public liability insurance protects the insured business against the third party claims that could arise due to damage to property, bodily injury or death that have occurred because of operation of the business.

Public liability insurance covers expenses involved in litigation.

If your business happens to be the one involving a lot of customers coming to your business premises, then you should consider taking this insurance.

For instance, if a customer who visits your premises, unfortunately trips and falls at your premises and gets injured, then you will be legally liable to pay him the cost of his medical expenses.

Public liability will cover these costs. Thus, it is very important for your business to be covered under this policy.

Product liability insurance

Product liability insurance is associated with liability resulted due to bodily injury or loss that occurred from the use of a product (defective) you sold.

Thus, if your business is associated with manufacturing, supplying or selling of products, you should consider taking product liability insurance to stay protected against financial claims.

For example, if a toy manufactured by your company is defective and causes harm or injury to your customer, then he can claim compensation for the loss.

This insurance compensates for both legal expenses as well as medical expenses incurred by the insured.

Product liability is only applicable for products that are manufactured or sold, and not for services rendered.

Liabilities arising from services are covered by professional indemnity insurance.

Professional indemnity insurance

Professional indemnity insurance is a compulsory coverage (in many countries) for professionals like lawyers, doctors, engineers, accountants, architects, insurance brokers and financial advisers.

It covers the liabilities arising due to inadvertent negligence, errors, omissions or loss of data by employees while executing the profession.

It also covers factors which are beyond the control of the insured.

For instance, while processing the data of a client, a small fault made by the employee leads to loss of data. In such cases, having professional indemnity insurance bears the expenses to be incurred.

Deciding the right package of business insurance is quite hard.

You should, however, see to it that you purchase insurance to cover every aspect of the risk involved in your business.

The most common insurance cover includes product liability, public liability and professional indemnity insurance.

All three policies are different from each other, but they are intended to protect your business from different risks of claims and liabilities. Hence, ensure that you have proper cover for your business against possible liabilities.

Published: Wednesday, 18th Aug 2021
Author: 331

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Life Insurance Articles

Consumer Protections for Life Insurance in Australia
Life insurance in Australia is supported by consumer protections covering disclosure documents, product design, cooling-off rights, claims handling, complaints and external dispute resolution. - read more
Life After You: Planning Ahead With Quality Life Insurance for Your Family
Life insurance is a fundamental component of a robust financial plan, yet its significance is often underestimated. It serves as a safety net, ensuring that your loved ones are financially secure in the event of your absence. Understanding life insurance is the first step towards safeguarding your family’s future. - read more
How Pre-Existing Conditions Influence Life Insurance Premiums
When it comes to life insurance, a pre-existing condition refers to any medical condition or illness that you have been diagnosed with before applying for a life insurance policy. - read more
Life Insurance and Estate Planning: What You Need to Know
Life insurance and estate planning are critical components of financial security. They ensure that your loved ones are protected financially when you are no longer around. By understanding these tools, you can take significant steps to secure your family's future. - read more
How life insurance claims work in Australia
A life insurance claim can feel difficult to navigate at an emotional time. This guide explains the usual steps beneficiaries follow in Australia, the documents commonly requested, how insurer assessment works, what may cause delays, and where to seek help if a claim is disputed. - read more

Insurance News

Live Music Insurance Reform Call Has Wider Lessons for Public-Facing Businesses
18 Nov 2026: Paige Estritori
A NSW parliamentary inquiry into the state of live music has put insurance affordability back in the spotlight, with its final report tabled on 9 November 2026 identifying public liability insurance as a major cost burden for venues and festivals. The recommendation does not change premiums immediately, but it gives business owners a useful signal: governments, insurers and industry groups are still grappling with how public-facing risks are priced, documented and managed. - read more
Storm Claims Put Policy Details Under Fresh Pressure
18 Nov 2026: Paige Estritori
The Insurance Council of Australia’s expanded Significant Event declaration for severe storms in Queensland and New South Wales is a timely reminder that insurance is tested in the messy aftermath of damage, power loss and disruption, not just at renewal time. By 17 November 2026, insurers had received more than 7,500 claims linked to severe weather from 11 to 17 November, with damage ranging from torn roofs and broken fences to water entry, hail impacts and spoiled food after outages. - read more
Bakery Dispute Shows Supplier Risk Can Interrupt Trade
18 Nov 2026: Paige Estritori
A recent business interruption dispute involving a bakery has given restaurant and cafe operators a timely reminder that disruption does not always start inside the insured premises. The Australian Financial Complaints Authority found in favour of a bakery retail business after its insurer declined a claim linked to a fire at the premises of its sole supplier, bringing supplier-dependency wording into sharp focus for hospitality businesses that rely on specialist producers, central kitchens, roasters, wholesalers or delivery partners. - read more
Freight Deadline Pressure Is Now an Insurance Risk Test
18 Nov 2026: Paige Estritori
The National Heavy Vehicle Regulator’s 16 November 2026 warning to put safety ahead of freight deadlines is more than a seasonal road-safety message. For transport operators, the Black Friday and pre-Christmas delivery rush is also a live risk-management test, with driver fatigue, vehicle checks, scheduling pressure and Chain of Responsibility duties all capable of influencing claims, liability exposure and future truck insurance discussions. - read more
Construction Safety Data Puts Tradie Insurance Reviews Back in Focus
18 Nov 2026: Paige Estritori
Safe Work Australia’s latest national work health and safety figures give trade businesses a timely reason to treat safety systems, claims records and insurance settings as connected issues rather than separate compliance tasks. Released on 12 October 2026, the Key Work Health and Safety Statistics Australia 2026 report records 222 worker fatalities in 2025 and shows construction continuing to carry a significant share of serious workplace harm. - read more

Start Here !
life insurance
Apply now for your free Insurance assessment and price comparisons!

Start Here:

Life Insurance Type:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Endorsement:
An amendment or addition to an existing insurance policy that changes the terms or scope of the original policy.