Life Insurance Australia :: Articles

Ambulance Cover: Do You Need It?

Do I need ambulance cover in Australia if Medicare doesn't include it?

Ambulance Cover: Do You Need It?

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

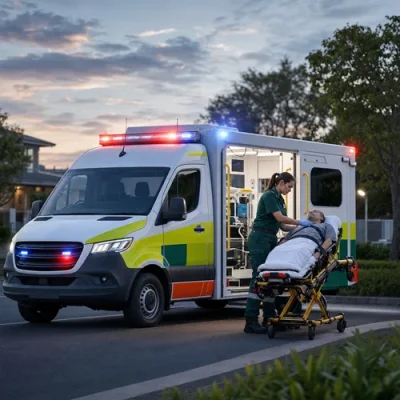
Medicare in Australia doesn't cover ambulance services or emergency transport. These services are more often covered by private health insurance. However, private funds are not the only ambulance and emergency transportation service providers available.
State governments also have their own ambulance and emergency transport services for community residents, and the costs of these services depend on the state in which you live. In some states, these services are free, but in others they may be costly enough for you to consider adding ambulance cover to your health insurance plan.
Ambulance cover can be confusing, especially when you consider that there are four different rules for emergency medical transportation services across Australia's seven states. If you live in QLD, NSW, or TAS for instance, ambulance services may be provided either through your local government or through the payment you make on your electricity bills.
Even still, these states do not pay 100 percent of the ambulance or emergency transportation costs, and you may not be covered at all outside of your home state, another reason to consider adding this service to your health insurance plan.
Of course, there are private health care funds that offer 100 percent ambulance cover, so you never need to worry about the cost of being transported to hospital in an emergency, no matter where you are.
By comparing health plans, you can find a policy that will pay for ambulance services and that meet your other health care needs as well, a real plus when you consider the bill for an ambulance can run $130 and more.
Residents of ACT, VIC, SA, NT and WA can purchase affordable ambulance cover through their local government.
However, the requirements to receive benefits for the full cost of the transport dictate that the ambulance service be medically necessary.
In other words, due to your condition or as a result of your medical emergency, you cannot be transported to hospital by any other means if you need immediate medical intervention. If ambulance cover is provided in your health insurance policy, make sure to read it carefully to understand if there are limitations on ambulance transport and if so, what they are.
Some health insurance funds provide ambulance cover automatically in certain specific policies they offer, so it is important to compare health insurance plans to see which provide this service in addition to other services you may want to secure.
Again, make sure you understand the terms of your ambulance cover, as many will have requirements for calling an ambulance to transport yourself or a loved one to hospital only when it is deemed medically necessary according to the terms of your health insurance provider.
Meeting the "medically necessary" requirement can mean any one or all of the following:
  • You must be transported to hospital or other approved medical facility by ambulance in order to receive immediate medical attention.
  • As an already admitted patient, you must be transferred to a separate hospital or facility for certain medical procedures.
  • You have called for an ambulance, but before it arrives you have received immediate professional care, then ambulance transport is no longer going to be covered.
  • An ambulance has been called, but in the meantime you receive immediate professional attention, then transport to the hospital is no longer covered.
  • When an air ambulance is required, you are covered when pre-approval has been obtained.
Ambulance Benefits are not payable under the following circumstances:
  • When any ambulance expense in already fully covered by private ambulance cover or state/territory ambulance plan. However, excess costs may be covered when the existing ambulance plan does not pay for the full amount of the services.
  • When you are transferred from one public hospital or approved center to another by ambulance while an admitted patient.
  • Once you are discharged from a hospital, you may not collect ambulance benefits for transportation.
  • When, as an admitted patient, you must be transported to another hospital for treatment because the admitting hospital does not have the facilities to care properly for you. Sometimes, the admitting hospital that orders your transfer will pick up the ambulance bill for you.
  • If you are 65 and live in WA, you are eligible for free or subsidized ambulance services. If you are eligible for subsidized services, you may be able to claim any uncovered cost from Medibank.
  • Residents of NSW ACT who already pay an ambulance levy as a part of your health insurance premium, and you are entitled to state ambulance cover, and if you have a Commonwealth concession card, you may be exempt from paying the state ambulance fee.
Of course, it's best to check with your local or state government to find out exactly what is and what is not covered under the ambulance transport scheme.
Remember, if you choose to purchase ambulance cover, or add it to your existing private health care plan, compare ambulance covers to find one with the most comprehensive coverage that fits within your budget.

Published: Sunday, 1st Aug 2021
Author: 273
Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Life Insurance Articles

Life insurance through superannuation in Australia: how it works
Many Australians hold life insurance through their super fund, sometimes without realising how it differs from a policy held outside super. This guide explains how insurance inside super works, how premiums and beneficiaries are handled, and what to check before relying on it. - read more
Life Insurance and Estate Planning: What You Need to Know
Life insurance and estate planning are critical components of financial security. They ensure that your loved ones are protected financially when you are no longer around. By understanding these tools, you can take significant steps to secure your family's future. - read more
How Pre-Existing Conditions Influence Life Insurance Premiums
When it comes to life insurance, a pre-existing condition refers to any medical condition or illness that you have been diagnosed with before applying for a life insurance policy. - read more
Consumer Protections for Life Insurance in Australia
Life insurance in Australia is supported by consumer protections covering disclosure documents, product design, cooling-off rights, claims handling, complaints and external dispute resolution. - read more
How life insurance claims work in Australia
A life insurance claim can feel difficult to navigate at an emotional time. This guide explains the usual steps beneficiaries follow in Australia, the documents commonly requested, how insurer assessment works, what may cause delays, and where to seek help if a claim is disputed. - read more

Insurance News

NHVR Prohibition Notice Puts Fleet Systems Under the Insurance Microscope
12 Nov 2026: Paige Estritori
A fresh National Heavy Vehicle Regulator action against a heavy vehicle operator is a timely reminder that insurance risk is not limited to what happens at the moment of a crash. The NHVR announced on 30 October 2026 that it had issued a prohibition notice after identifying significant and ongoing safety risks, including repeated defects in safety-critical systems and concerns about the operator’s management controls. - read more
Diagnosis timing is not the only test for income cover
12 Nov 2026: Paige Estritori
A recent income protection dispute has put fresh attention on a difficult but important issue for Australian workers: a medical condition may be treated as pre-existing even where a formal diagnosis comes later. The case, reported on 9 November 2026, involved a prostate cancer claim that was declined after the Australian Financial Complaints Authority accepted that earlier medical warning signs and specialist investigations were enough to trigger a pre-existing condition exclusion. - read more
Fuel Recovery Order Restarts, Raising Insurance Budget Questions
12 Nov 2026: Paige Estritori
The Fair Work Commission’s varied fuel cost recovery order will restart obligations from 23 November 2026, requiring covered road transport contractual chains to account for higher fuel costs against the 6 March 2026 benchmark. For truck operators, the immediate issue is contract pricing, but the insurance angle is also important: cash flow, route choices, subcontracting arrangements and vehicle utilisation all influence how risk is presented and managed. - read more
Court Ruling Highlights Why TPD Wording Matters for Business Owners
12 Nov 2026: Paige Estritori
A Queensland Court of Appeal decision involving AIA Australia has put renewed attention on how technical policy conditions can affect total and permanent disability claims, and why business owners should not treat insurance wording as a background detail. The case concerned group TPD cover held through superannuation, but its broader message is relevant to SMEs that rely on life, TPD and disability-style cover to protect debt, ownership arrangements and business continuity. - read more
Latest Claims Data Shows Why Policy Structure Still Matters
12 Nov 2026: Paige Estritori
APRA’s latest life insurance claims and disputes statistics, released on 16 October 2026 and covering the 12 months to 30 June 2026, provide a useful reminder for Australian businesses: the practical value of cover often depends on how clearly it is structured, documented and understood before a claim ever arises. - read more

Start Here !
life insurance
Apply now for your free Insurance assessment and price comparisons!

Start Here:

Life Insurance Type:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Liability Insurance:
A type of insurance that provides protection against claims resulting from injuries and damage to people and/or property.