
Life Insurance Australia :: Articles

The 5 most common Business Insurance mistakes

What are the most common mistakes business owners make with insurance?

The 5  most common Business Insurance mistakes

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Looking over your insurance premiums each year, you may be wondering how you could save a dollar or two on your next premium. As an intangible asset, it can be difficult to put a value on insurance ... until something goes wrong and you need to claim. In this article, we highlight the five most common mistakes that business owners make when evaluating their insurance requirements:

Not understanding your full Risk Profile

When reviewing your insurance needs, it's essential to sit down and determine what types of events could occur in your business that would create adverse impact. From there, you need to determine what would have the biggest business impact - in terms of dollars, time and effort. Then you need to work out how to ensure that you are adequately covered against these risks.
Often policy holders will do away with one part of a policy thinking that they can save money. For example, they will go for theft, fire and glass coverage, but not take out burglary even though it's a relatively minor additional fee.
It is Murphy's Law that the one thing you leave out is the one thing you need to claim for on your insurance. And it can be for the most oddest of items. The strangest story I've heard of is a fish and chip shop that was robbed of all their frozen fish. Although it was never proven, it was suspected that a competitor fish and chip shop, just around the corner, decided that they wanted a freezer full of product to sell without the set up costs!

Not disclosing everything!

Yes, it is true ... if you don't disclose everything upfront when you sign up your insurance policy, the insurance company is quite within their rights to not pay out on your claim. Worst still, they won't even refund your premium paid to date. Therefore, don't hold back. Disclose anything relevant to your insurance upfront to save any drama's at a later date.

Insuring assets at written down value instead of replacement value.

It is essential that you insure your assets for REPLACEMENT value. In other words, how much would it cost you to repurchase the items insured at full price. A common mistake, particularly when purchasing an existing business, is to insure the assets at the "written down" (or depreciated) value, rather than replacement cost.

Being "cheap" on your premium

Don't get caught out by trying to save yourself a few hundred dollars on your insurance premium, to the detriment of being fully insured. Being cheap now could end up costing you thousands of dollars down the track.

Not listening to your Insurance Broker

Your insurance broker is the best person to advise you on insurance cover. Having seen many similar businesses to yours, they have seen other business owners go through the pain that you don't need to. Your insurance broker will know what works for your type of business and how to get it for the cheapest possible price. As an insurance agent, they know the ropes and can maneuver you through the subtleties in insurance policies which will save you dollars in the long term.
It's a quick, efficient and cheap way to grow your profits immediately!

Published: Sunday, 1st Aug 2021
Author: 62

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Life Insurance Articles

Trauma Cover: Calculating Adequate Protection for Life's Unexpected Moments
The financial fabric of our lives consists of both planning and safeguarding against the unforeseen. Trauma cover, a lesser-known but crucial aspect of personal insurance, provides this protection by offering a lump sum payment upon diagnosis of specific serious illnesses or injuries. In the tapestry of financial planning, it acts as a vital safety net, ensuring that unexpected health crises do not lead to monetary distress. - read more
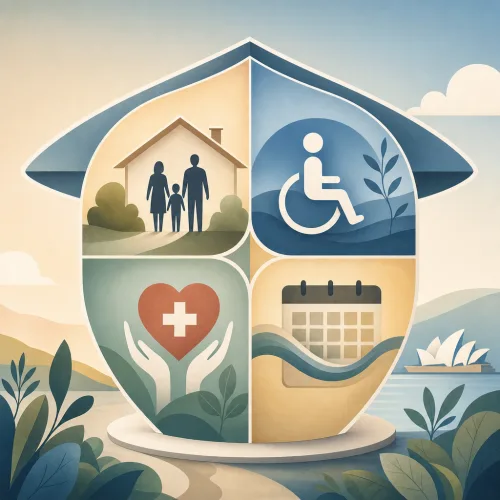
Types of life insurance in Australia: life cover, TPD, trauma cover and income protection
A clear guide to the main types of personal insurance Australians often consider: life cover, TPD insurance, trauma cover and income protection insurance. - read more
Life Insurance Comparison: Key Questions to Ask Your Insurer
Life insurance is a crucial consideration for middle-aged to older Australians. It provides financial security for your loved ones in the unfortunate event of your death. Understanding the various options available is vital to making an informed decision. - read more
How to Review and Update Your Life Insurance Policy as Your Family Grows
Life insurance is an essential safety net for families, providing financial security when it's needed the most. As your family grows, the importance of having a well-structured life insurance policy becomes even more critical. In the busy lives we lead today, it’s easy to overlook this crucial aspect of financial planning. However, ensuring your coverage meets your family's evolving needs is vital. - read more
TPD insurance in Australia: what total and permanent disability cover means
TPD insurance can provide a lump sum if you become totally and permanently disabled and meet your policy's definition. Learn how TPD cover works in Australia, how it relates to life insurance, and what to compare before applying. - read more

Insurance News

Why rising builder failures matter for contract works cover
17 Sep 2026: Paige Estritori
Australia's construction sector remains under pressure, with recent insolvency figures continuing to show building and construction as one of the most exposed parts of the economy. Higher material costs, tight margins, labour shortages, delayed payments and fixed-price contract stress have all contributed to a tougher operating environment for builders, subcontractors and project owners. - read more
How Softer Truck Sales Can Affect Insurance Decisions
17 Sep 2026: Paige Estritori
Recent transport industry sales updates point to a more selective new-truck market, with operators weighing replacement timing against finance costs, emissions planning, availability and contract confidence. For truck businesses, that matters well beyond the showroom. A change in buying momentum can flow through to vehicle values, repair economics, insurer appetite and the way fleets should set insurance sums before renewal. - read more
Cyber Scam Alerts: What Trade Businesses Should Check Now
17 Sep 2026: Paige Estritori
Fresh small business cyber warnings are a practical reminder that digital risk is no longer just a concern for large companies with complex IT systems. For Australian tradespeople, the most damaging cyber incident may be far simpler: a fake invoice, altered bank details, a compromised email account or a scam message that looks like it came from a supplier, builder, real estate agent or client. - read more
Why Super Service Standards Matter for Your Income Protection
17 Sep 2026: Paige Estritori
ASIC’s continuing focus on superannuation member services has put another practical issue in front of Australian workers: insurance inside super is not just about whether cover exists, but whether members can understand and use it when they need help. Recent regulatory attention on trustee administration, communication and claims support is a timely reminder for anyone relying on salary continuance or income protection benefits through their fund. - read more
What More PBS Trucking Means for Insurance Cover
17 Sep 2026: Paige Estritori
Recent transport industry reporting has again highlighted growing interest in Performance Based Standards vehicles and other high-productivity truck combinations across Australia. For operators, the attraction is clear: fewer trips, better payload efficiency and stronger productivity on approved routes. For insurers, however, the shift is not simply a matter of adding another truck to the schedule. PBS combinations can alter exposure across vehicle value, route compliance, load responsibility, driver capability and recovery after an incident. - read more

Start Here !
life insurance
Apply now for your free Insurance assessment and price comparisons!

Start Here:

Life Insurance Type:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Term Life Insurance:
A form of life insurance that is a pure protection policy with no cash or maturity value which lasts for a specific length of time, called a term.