Life Insurance Australia :: Articles

Understanding the Differences: Income Protection vs Total and Permanent Disability Insurance

What are the main differences between income protection and TPD insurance?

Understanding the Differences: Income Protection vs Total and Permanent Disability Insurance

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

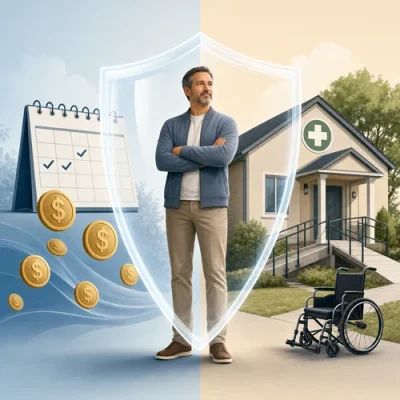
Income protection insurance is a type of policy that provides financial support to individuals who are unable to work due to an illness or injury. The insurance company will pay a portion of the policyholder's earnings, which can be used to cover everyday living expenses and bills. This type of insurance is different from total and permanent disability insurance (TPD) in a few key ways.

One of the main differences is that income protection insurance generally covers only 75% of the first $20,000 of the policyholder's gross monthly income, and 50% of gross monthly income that exceeds $20,000 per month. This gap is meant to incentivize policyholders to return to work. Additionally, there is often a waiting period before benefits start to be paid. The longer the waiting period, the lower the premiums.

TPD, on the other hand, provides a lump sum payment to individuals who are permanently unable to work in their occupation or in any occupation for which they are suited by training, education or experience, or if they've lost the ability to function cognitively or physically. The money can be used for things like modifying a home, medical care or procedures.

Another key difference is the amount insured under income protection cover is usually limited to 75% of the policyholder's income, whereas the amount insured under a TPD policy can vary.

Many people have their income protection insurance, life insurance or TPD insurance built into their superannuation. This can have advantages such as lower costs and potential tax benefits, but it's worth noting that all benefits within superannuation, including insurance proceeds, are subject to Superannuation Industry Supervision legislation. It can be difficult to satisfy the legislation's definition of "permanent disability", which can make it more restrictive than definitions used by insurance companies.

Overall, income protection insurance is a valuable option for those who want to ensure they have financial support if they are unable to work due to an illness or injury. It is different from TPD in that it provides an income stream, rather than a lump sum payment, and the amount insured is generally limited to 75% of the policyholder's income. 

Published: Friday, 27th Jan 2023
Author: Paige Estritori

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Life Insurance Articles

Maximize Your Safety Net: Top Tips for Optimizing Income Protection Benefits
Welcome to a pivotal guide dedicated to empowering you with the essentials of income protection insurance in Australia. As we navigate through times of uncertainty, safeguarding your financial wellbeing becomes not just a priority, but a necessity. Income protection insurance stands as one of the key pillars of financial security, ensuring a steady flow of income during periods when you're unable to work due to illness or injury. - read more
The Digital Age of Insurance: Keeping Costs Down with Online Quotes
The horizon of the insurance industry has undergone a transformative shift with the advent of digital technology. With a few clicks, consumers can navigate the once-complex world of insurance policies from the comfort of their home. The digital landscape for insurance services offers unprecedented access to information, comparisons, and instant communication, fostering a more empowered insurance client. - read more
How Pre-Existing Conditions Influence Life Insurance Premiums
When it comes to life insurance, a pre-existing condition refers to any medical condition or illness that you have been diagnosed with before applying for a life insurance policy. - read more
Life After You: Planning Ahead With Quality Life Insurance for Your Family
Life insurance is a fundamental component of a robust financial plan, yet its significance is often underestimated. It serves as a safety net, ensuring that your loved ones are financially secure in the event of your absence. Understanding life insurance is the first step towards safeguarding your family’s future. - read more
How to Determine How Much Life Insurance Cover You May Need
Life insurance can help provide a financial safety net for the people who depend on you. The right cover amount is not a single fixed figure: it depends on your income, debts, family responsibilities, future goals, savings and the type of policy you choose. - read more

Insurance News

Insurance Inquiry Delay Extends Wait for Small Business Answers
04 Nov 2026: Paige Estritori
A federal parliamentary inquiry examining small business insurance has pushed its final report from 27 October 2026 to 26 February 2027, extending the wait for recommendations on affordability, availability and regulation. For Australian businesses that rely on public liability insurance, the delay matters because the inquiry is looking directly at whether modern cover is meeting the needs of small firms, not-for-profits and community organisations. - read more
Life Claims Review Puts Communication Back in Focus
04 Nov 2026: Paige Estritori
A new Life Code Compliance Committee inquiry has sharpened attention on how life insurers manage longer-running total and permanent disability and income protection claims, finding that earlier information requests and clearer communication could reduce avoidable delays for people already dealing with illness, injury or loss of income. - read more
Why Liability Pricing Relief Still Needs Caution in Restaurants
04 Nov 2026: Paige Estritori
Australian restaurants and cafes may be entering a more competitive phase for liability insurance, but the latest market analysis suggests owners should avoid treating softer pricing as a signal that risk has reduced. KPMG Australia's October 2026 liability insurance review, drawing mainly on APRAs National Claims and Policies Database to December 2024, points to moderating pricing momentum after several years of premium strengthening, while also highlighting uneven claims experience across public liability and related classes. - read more
Commercial Insurance Softens, but Truck Cover Still Needs Evidence
04 Nov 2026: Paige Estritori
Fresh commercial insurance data points to a more buyer-friendly market, but Australian truck operators should be careful not to read the headline fall as a simple forecast for cheaper heavy vehicle cover. Marsh’s Q3 2026 Global Insurance Market Index, released on 21 October 2026, reported a 12 per cent fall in Pacific commercial insurance rates for the quarter, led by property and supported by strong insurer competition. - read more
Softer Commercial Insurance Market Gives Tradies More to Weigh Up
04 Nov 2026: Paige Estritori
Australian trade businesses heading into renewal season may find the commercial insurance market more competitive than it has been for several years, with recent industry updates pointing to softer pricing across several business insurance classes. For tradies, that does not automatically mean every premium will fall, but it does create a useful moment to review whether cover still matches the way the business actually works. - read more

Start Here !
life insurance
Apply now for your free Insurance assessment and price comparisons!

Start Here:

Life Insurance Type:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Umbrella Policy:
An additional insurance policy that provides extra liability coverage beyond the limits of the insured's primary policies.